Spring Begins With Auction Activity Still Well Below Last Year
Australia’s property market has entered spring, but the latest auction numbers suggest the seasonal lift is yet to translate into a major increase in buyer activity. Across the combined capital cities, 1,462 homes went to auction, unchanged from the previous week and 31.1% below the same week last year. The preliminary clearance rate edged up to 52.7%, only slightly above the previous week’s 52.4% and just 0.4 percentage points above the winter average. Melbourne recorded the most auctions at 662, with its preliminary clearance rate improving to 58.2%. Sydney also strengthened, reaching 57.7%, its highest preliminary clearance rate in 18 weeks. Meanwhile, Brisbane and Adelaide were noticeably softer, with clearance rates of 24.8% and 34.5% respectively.
The broader market remains mixed. Home values across the combined capitals fell 1.1% over the latest 28 days, while rental conditions continue to provide a different story, with the national median rent now $711 per week, up 5.7% over the past year. Overall, spring is bringing more activity, but not yet the kind of widespread buyer urgency that would suggest the market is heating up again.
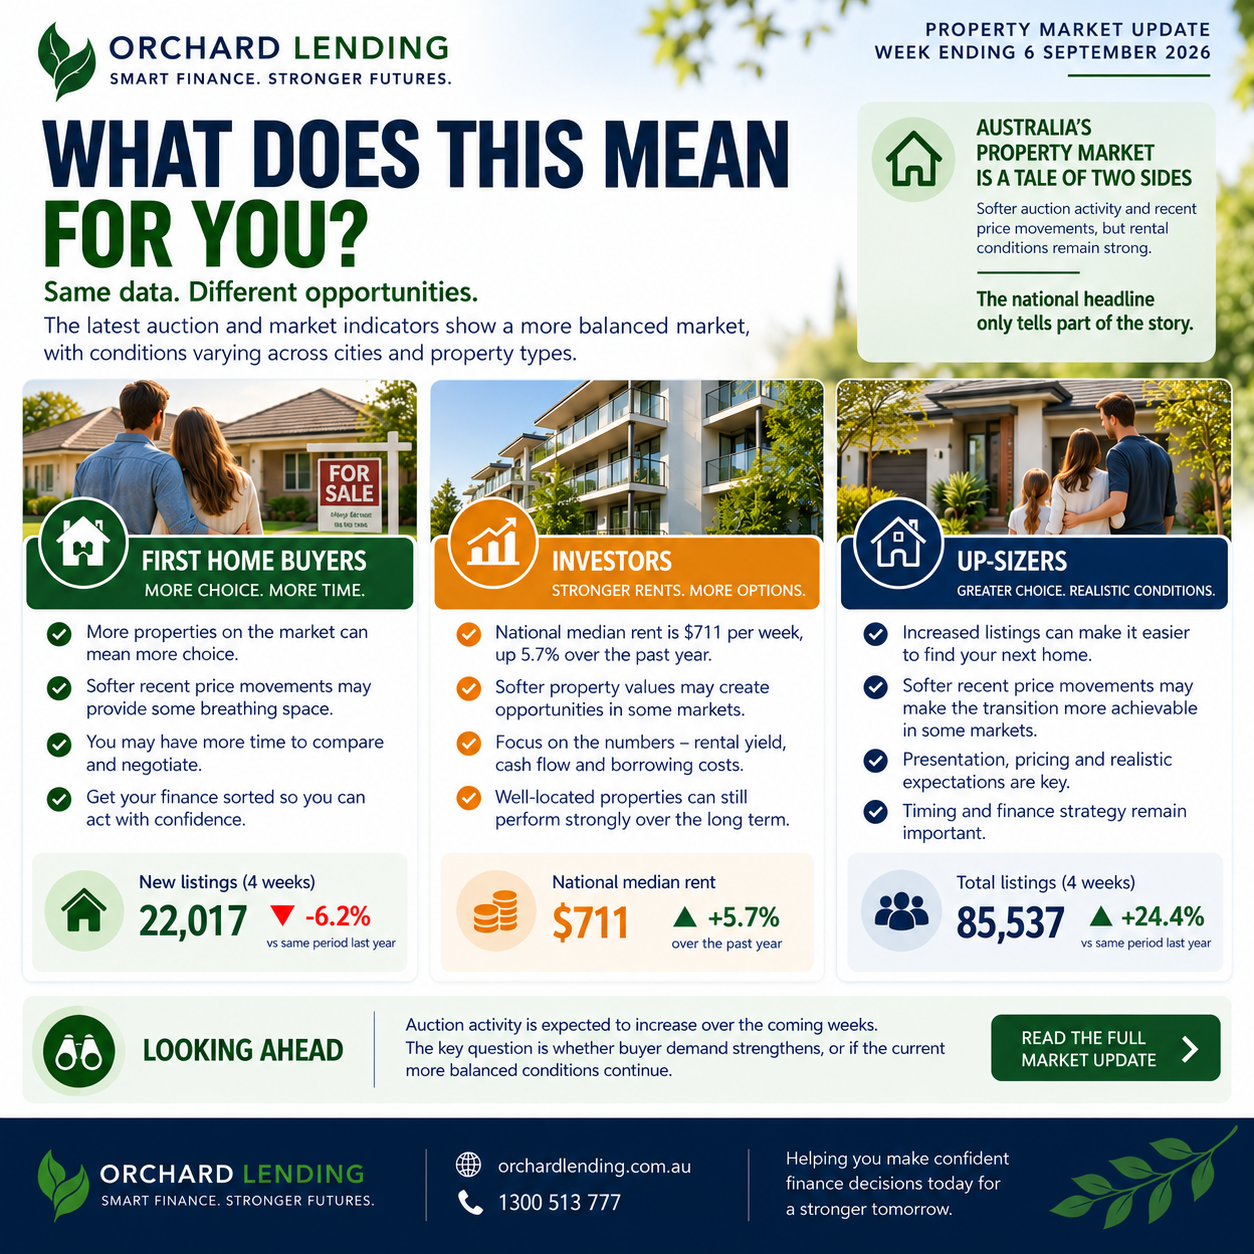
What This Means For
First Home Buyers
More properties remaining on the market can mean more choice and potentially greater negotiating room. Softer short-term price movements may also provide some breathing space, although competition can still vary considerably between cities and suburbs.
Investors
Rental growth remains one of the stronger parts of the market, with the national median rent up 5.7% over the year. Softer property values may improve opportunities in some markets, but the individual property’s cash flow, borrowing costs and purchase price remain critical.
Up-Sizers
Increased listings can provide more choice when looking for the next home, while softer recent price momentum may make the transition easier in some markets. The key is managing the timing and finance of selling and buying.
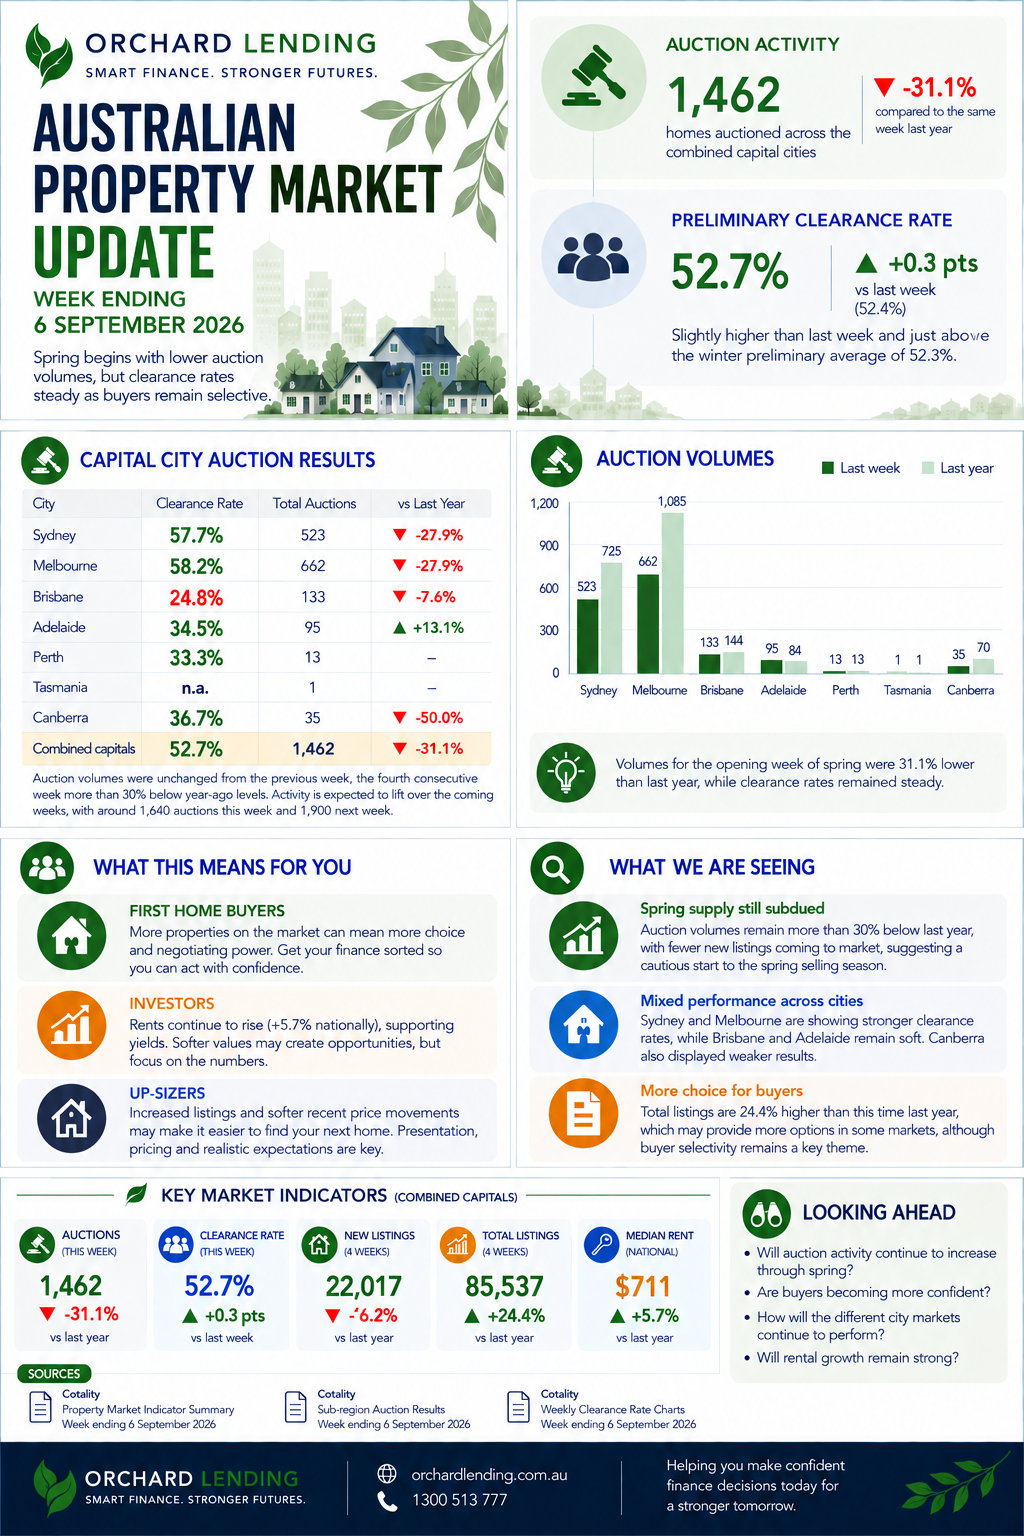
Auction Clearances In Select Markets
This week’s preliminary auction results show a fairly wide spread between markets. Melbourne and Sydney recorded the strongest major-capital clearance rates, while Brisbane and Adelaide were considerably softer.
The regional results also highlight just how different local property markets can be. Newcastle and Lake Macquarie recorded a 90.9% preliminary clearance rate, while Melbourne’s Outer East reached 75.0%. At the other end, Melbourne’s Mornington Peninsula recorded 30.0%.
Selected higher clearance rates:
- Newcastle and Lake Macquarie, NSW: 90.9%
- Melbourne Outer East, VIC: 75.0%
- Melbourne South East, VIC: 68.0%
- Melbourne North West, VIC: 64.2%
- Sydney Inner South West, NSW: 63.0%
Selected lower clearance rates:
- Melbourne Mornington Peninsula, VIC: 30.0%
- Brisbane: 24.8%
- Adelaide: 34.5%
- Canberra: 36.7%
- Melbourne West, VIC: 38.1%
These are preliminary results, and some regions have relatively small auction volumes, so they should be treated as a snapshot rather than a definitive ranking of market strength.
Key Market Indicators
| Indicator | Latest |
|---|---|
| Capital-city auctions | 1,462 |
| Preliminary clearance rate | 52.7% |
| New listings, 4 weeks | 22,017 |
| Total listings, 4 weeks | 85,537 |
| National median rent | $711 |
| Annual rental growth | 5.7% |
The latest listings data covers the four weeks ending 6 September 2026. New listings were 6.2% below the same period last year, while total listings were 24.4% above last year’s level.
Questions We’re Hearing
Is the property market getting stronger as spring begins?
Auction activity is expected to increase over the coming weeks, but the latest clearance rate remains close to the winter average. The next few weeks should give us a better indication of whether the seasonal increase in activity is being matched by stronger buyer demand.
Are buyers getting more choice?
The latest listings data shows total advertised stock remains below last year’s level, so the picture is not quite as simple as “more properties everywhere”. However, conditions vary considerably between markets, and some buyers may still find more negotiating room than they had during stronger periods.
Which markets are performing best?
The answer depends on what we’re measuring. Melbourne and Sydney currently have stronger major-capital auction clearance rates, while Brisbane and Adelaide are softer. Home-value performance also differs considerably between cities, so the national headline only tells part of the story.
The Orchard Lending View
Spring is here, but the market hasn’t suddenly turned into a buying frenzy.
The latest numbers suggest more activity is coming through, but buyer demand remains selective. Melbourne and Sydney are showing stronger auction results, while Brisbane and Adelaide are noticeably softer. For buyers, that can create opportunities to take a little more time and negotiate rather than feeling forced into a decision. For sellers, it reinforces the importance of realistic pricing and understanding what comparable properties are actually achieving. The broader market is still moving in different directions, and the property you’re actually buying matters far more than the national headline.
What We’ll Be Watching Next Week
As we move further into spring, there are a few things we’ll be keeping an eye on:
Auction activity – Will the expected increase in auction numbers continue, and will stronger activity translate into higher clearance rates?
Buyer demand – Are buyers becoming more confident, or are they continuing to take their time and negotiate as more properties come onto the market?
Differences between markets – Sydney and Melbourne are currently showing a different pattern to Brisbane and Adelaide. We’ll be watching to see whether those gaps widen or begin to narrow.
Rental conditions – With rents continuing to rise nationally, we’ll be watching whether rental growth remains strong and how this continues to affect investors and housing affordability.
Next week we’ll see whether the spring market starts to show a little more momentum, or whether buyers remain firmly in the driver’s seat….